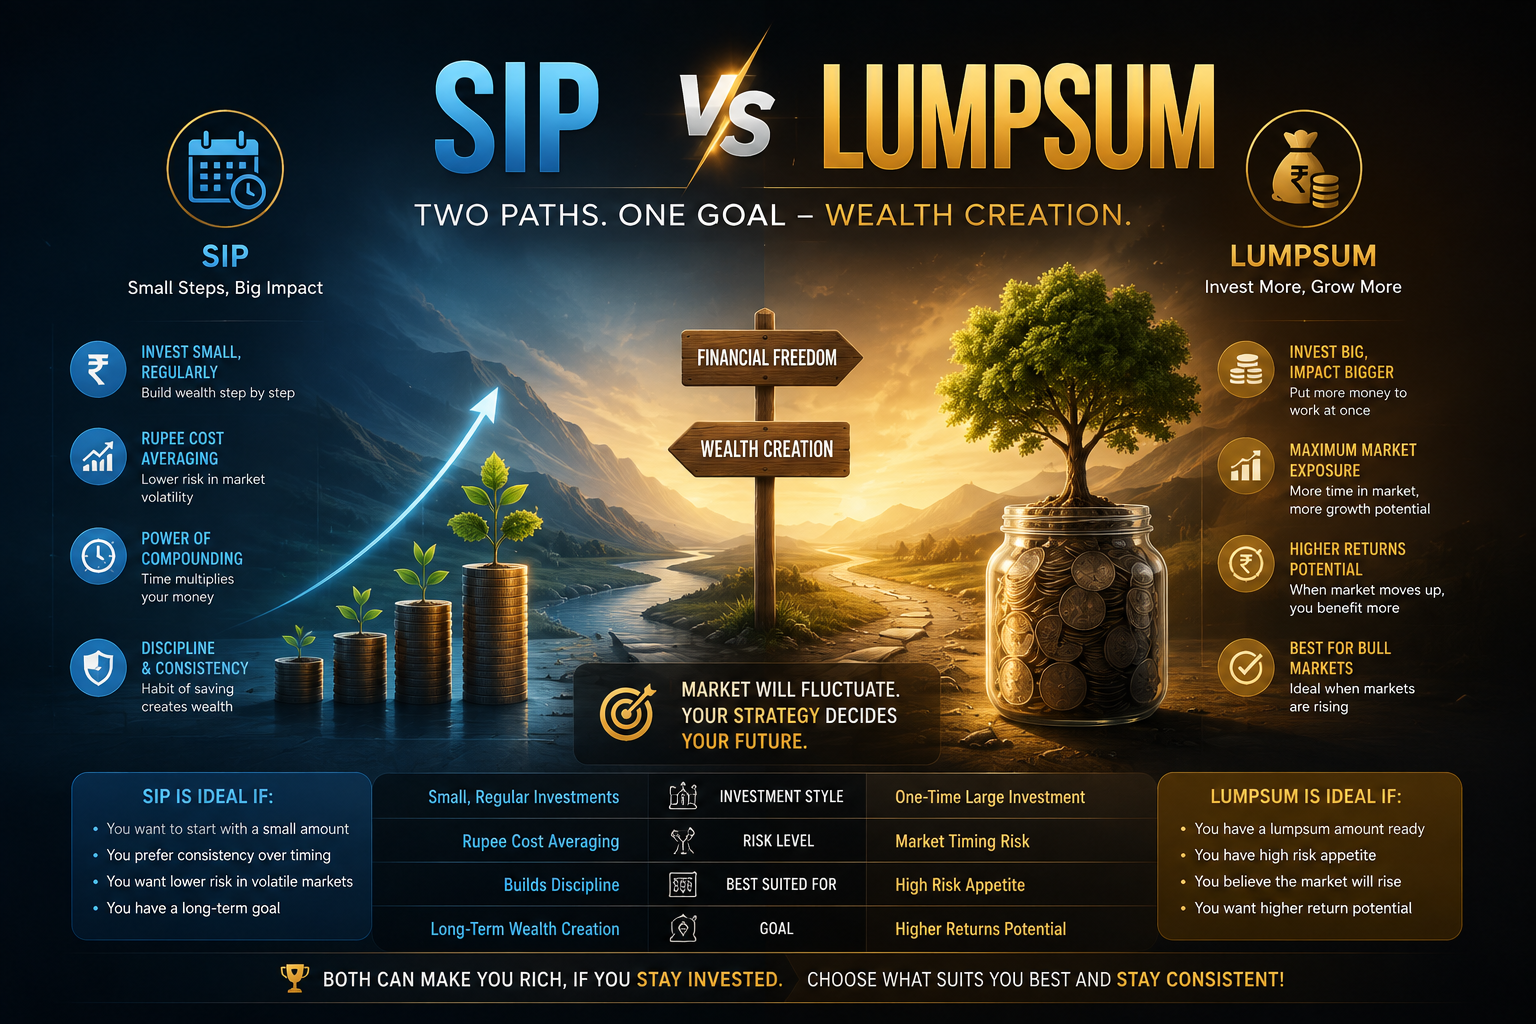
SIP vs lump sum is one of the most common questions investors face when deciding how to put their money to work for the long term.
SIP vs Lump Sum: Which One Should You Choose?
When you decide to invest for the long term, an important question often comes up:
Should you invest a fixed amount regularly, or put a larger amount into the market at once?
That is the basic idea behind the SIP vs lump sum comparison.
Both approaches have a place in investing. The more suitable option depends on factors such as your income, available money, financial goals, investment horizon and comfort with market fluctuations.
Before comparing the two, it helps to understand how each approach works.
What Is SIP?
SIP stands for Systematic Investment Plan.
In the mutual fund context, a SIP allows an investor to invest a specified amount at regular intervals. SEBI describes SIP as a facility through which investors can make regular investments of a fixed amount.
For example, instead of investing $6,000 at once, an investor could invest $500 every month for 12 months.
The amount and frequency can vary depending on the investment product and provider.
Regular fixed-amount investing also means that the number of units purchased can change as prices move. A lower price allows the same amount of money to buy more units, while a higher price buys fewer units. This idea is commonly associated with dollar-cost averaging. (Investor.gov)
One important distinction is worth remembering: SIP is a way of investing regularly, not an investment product or asset class by itself.
What Is Lump-Sum Investing?
Lump-sum investing means putting a larger amount of money into an investment in a single transaction rather than spreading that particular amount across several scheduled contributions.
Consider an investor with $20,000 available for a long-term goal. Instead of dividing the money into monthly contributions, they could invest the amount at once.
The main difference comes down to timing.
With a lump sum, the money enters the investment immediately. A SIP, on the other hand, spreads those investments across multiple dates.
SIP vs Lump Sum: The Key Difference
The easiest way to understand the difference is to look at when your money enters the market.
| SIP | Lump Sum |
|---|---|
| Money is invested regularly | Money is invested at once |
| Can suit income that becomes available gradually | Can suit investors who already have a larger amount |
| Purchases take place at different prices | The investment is exposed to market movements from the investment date |
| Spreads the timing of purchases | Provides immediate market exposure |
| Encourages a regular investing habit | Requires a larger amount to be available |
Neither approach automatically produces better returns.
The outcome depends on several factors, including the investment chosen, market performance, costs, taxes and how long the money remains invested.
When SIP May Make More Sense
For someone whose investable income arrives regularly, SIP can be a convenient way to build an investment habit.
Imagine a person who receives a monthly salary and wants to invest part of it for a long-term goal. Rather than waiting for a large amount to accumulate, they could invest a fixed amount at regular intervals.
There is also a timing benefit to consider. Because purchases occur on different dates, the investor doesn’t put the entire amount being accumulated through those contributions into the market on one particular day.
When prices decline, the same fixed contribution buys more units. During periods of higher prices, it buys fewer. This can help spread the purchase prices over time, although it does not guarantee profits or prevent losses.
The underlying investment can still fall in value.
When Lump Sum May Make More Sense
Lump-sum investing becomes relevant when you already have a significant amount available for investment.
Perhaps you received a bonus, inheritance or another financial windfall. After setting aside money for important expenses and considering your financial goals, you may decide to invest some of the remaining amount.
Putting that money to work immediately gives you market exposure from the start.
A rising market could work in favour of the lump-sum investor because the full amount was already invested. However, a decline soon after investing would expose the entire amount to that fall.
That makes the investor’s ability to handle short-term market movements an important consideration.
Does SIP Reduce Investment Risk?
This is one of the most important points to understand.
SIP does not make an investment risk-free.
The underlying investment still determines most of the investment risk. If its value falls, an investor using a SIP can also experience losses.
What regular investing changes is the timing of purchases. Instead of investing the entire amount on one date, contributions are made at different points in time.
Investor.gov describes dollar-cost averaging as investing equal portions at regular intervals regardless of market movements. The approach can provide a consistent investment process, but it does not guarantee a profit or protect an investor from losses.
So, SIP should be viewed as an investment method, rather than a protection against market losses.
A Simple Example
Suppose two investors each plan to invest a total of $12,000.
Investor A: Regular Investing
Investor A invests:
$1,000 × 12 months = $12,000
The purchases take place at different prices throughout the year.
Investor B: Lump Sum
Investor B invests:
$12,000 × 1 = $12,000
The entire amount enters the market at the beginning.
Now imagine that the market rises soon after Investor B invests. Because the entire amount was already invested, the lump-sum approach could benefit from that increase.
A different outcome is possible if the market falls soon after the investment. Investor B would see the entire $12,000 affected by that decline, while Investor A would have had only part of the planned amount invested at that point.
Future contributions from Investor A would still be exposed to whatever prices existed at those later dates.
This example shows why the timing of investments can affect the outcome. It does not demonstrate that SIP will always outperform lump-sum investing, or that lump sum will always be superior.
SIP vs Lump Sum: Which Is Better?
There is no universal winner.
SIP may be suitable if:
- Your investable money becomes available regularly.
- You want to invest gradually.
- A structured investing routine suits you.
- You don’t currently have a large amount available.
- Spreading purchases across different dates makes you more comfortable.
Lump sum may be suitable if:
- You already have a significant amount available.
- Your emergency savings and other important financial needs have been considered.
- You have a long-term investment plan.
- You are comfortable with the possibility of short-term market fluctuations.
The right choice depends on your circumstances rather than on one method being universally better.
Common Mistakes Investors Should Avoid
1. Treating SIP as risk-free
Regular investing doesn’t remove the risks associated with the underlying investment.
2. Assuming regular investing guarantees better returns
A regular investment schedule changes how money enters the market. It cannot guarantee a particular return.
3. Investing money you may need soon
Money required for near-term expenses should be considered separately from money intended for long-term investment goals.
4. Ignoring fees and taxes
Investment costs and applicable taxes can affect your overall results. Since tax rules and investment costs vary between countries and products, check the rules that apply to your situation.
5. Choosing the method before defining the goal
Start with the financial goal.
Once the goal, time horizon and financial circumstances are clear, you can consider which investment approach makes sense.
So, Which One Should You Choose?
Instead of asking:
“Is SIP better than lump sum?”
A more useful question is:
“Which approach fits my financial situation and investment plan?”
Someone who receives investable income regularly may find regular contributions easier to maintain.
An investor who already has a larger amount available may consider investing it as a lump sum, provided that the approach fits their goals and ability to handle market movements.
The two approaches also don’t have to be treated as completely separate choices. An investor could make regular contributions from ongoing income while separately deciding how to deploy a larger amount that is already available. Learn more about smart money moves to optimize your investment strategy.
Final Thoughts
The SIP vs lump sum debate can make investing sound more complicated than it really is.
At its core, the difference is straightforward.
SIP spreads investments across multiple dates.
Lump-sum investing puts a larger amount into the market at one point in time.
Neither approach guarantees better returns.
Your income, available capital, financial goals, investment horizon and ability to tolerate risk all matter when deciding how to invest.
Before putting your money into any investment, make sure you understand what you’re buying and the risks involved. Money needed for important short-term expenses should also be considered before committing funds to a long-term investment.
Invest with a plan, understand the risks and choose an approach that fits your circumstances.
Disclaimer
This article is for general educational purposes only and does not constitute investment, financial, tax or legal advice.
Investment products, regulations, taxes and investor protections vary between countries. Always review the relevant information and consider your individual circumstances before making an investment decision.
Leave a Reply