A friend once told me she hadn’t opened her banking app in three months. Not because she was doing fine because she was terrified of what she’d see. Sound familiar? You’re not the only one navigating your finances with one eye closed.
Nobody warned you it would feel like this. Prices are up, interest rates are still biting, and that “financially stable” version of yourself you planned to be by now? Still waiting in the wings. If you’re trying to figure out how to manage money in uncertain times, you’re not alone and you’re not failing. The economy is genuinely hard right now. But here’s the uncomfortable truth: uncertainty isn’t going away. So the goal isn’t to wait it out. It’s to build something solid inside the chaos.
This isn’t a generic “cut your lattes” article. These are real strategies for real economic pressure the kind most personal finance tips skip right over.
Build Your Emergency Fund Before Anything Else
Seriously. First, think about investing. Then consider paying down low-interest debt. Do this before anything else.
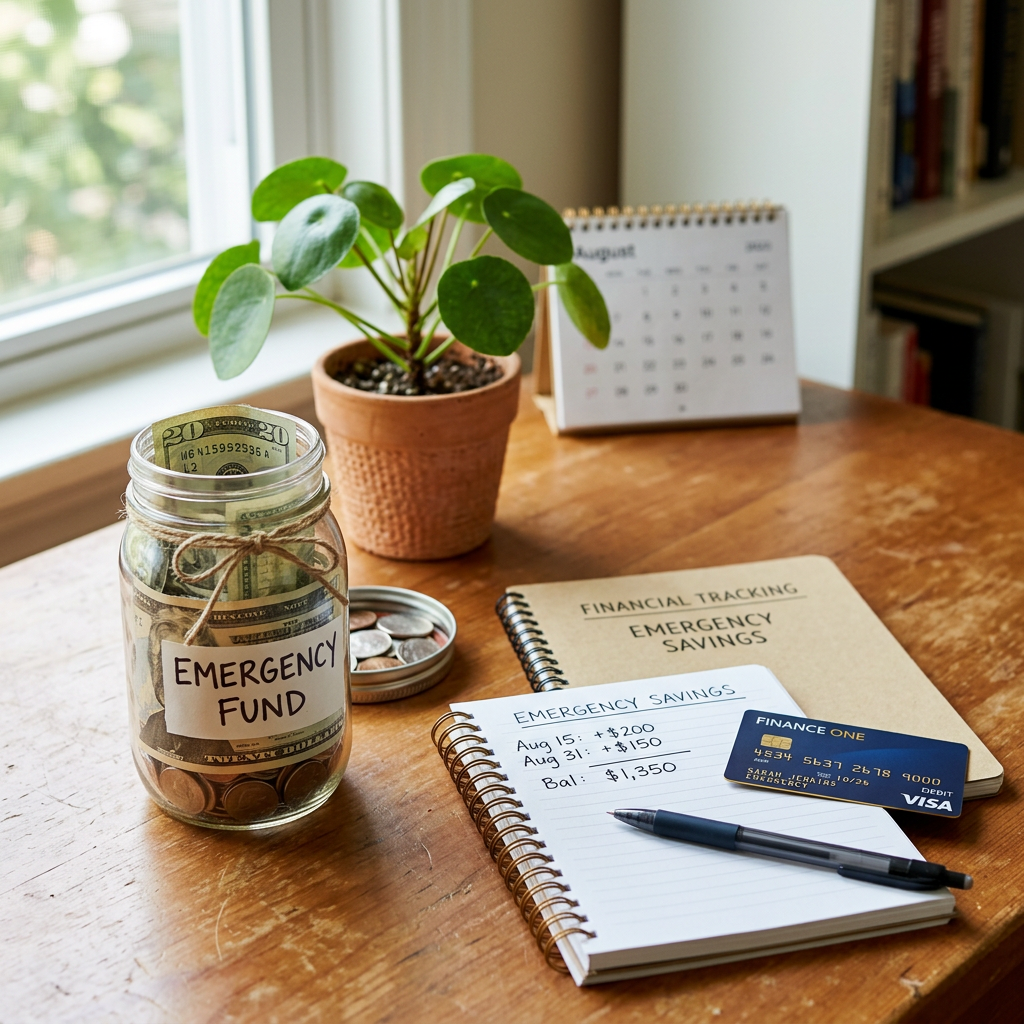
An emergency fund isn’t a luxury it’s your financial immune system. When the cost of living spikes and your paycheck doesn’t, that cushion is the only thing standing between you and high-interest debt. Most financial advisors say 3–6 months of expenses. Honestly? In 2026, with job market volatility what it is, I’d aim for 6.
Start small. If you can’t save $1,000 right now, save $200. Then $500. Progress beats perfection every single time. Keep this money in a high-yield savings account somewhere it earns something, but isn’t so accessible you’ll raid it for a weekend trip.
How Much Is Actually Enough?
Your emergency fund isn’t savings. It’s the floor beneath your feet when everything else gives way.
If you’re self-employed or in a cyclical industry, push toward 9.
One thing people get wrong: they build the fund, then stop. Your target should move with your life. If your rent just jumped 18% which, if you’re in a mid-size city right now, is entirely possible your emergency fund target just went up too. Recalculate every six months.
Stop Blaming Inflation, Start Auditing Your Life
Inflation is real. Budgeting during inflation is hard. But inflation also gets used as a catch-all excuse for not looking closely at where the money actually goes. That’s worth questioning.
Do a spending audit not a budget, an audit. Pull up your last 90 days of bank statements. Categorize everything. You’re looking for three things: subscriptions you forgot about, spending that doesn’t match your stated priorities, and patterns you’re embarrassed by not to shame yourself, but so you can actually see what’s going on and start untangling emotional spending.
The Simple Audit Method
- Download 90 days of bank and card statements.
- Sort every transaction into: Needs, Wants, Waste.
- Total each column. The Waste number will surprise you.
- Cancel or pause anything in Waste that you haven’t touched in 60 days.
- Redirect that money automatically into savings or debt repayment.
A spending audit isn’t about guilt. It’s about reclaiming the money you’re already earning.
According to Investopedia guide on zero-based budgeting, assigning every dollar a job before the month begins is one of the most effective ways to survive income pressure. It sounds extreme. It’s actually just intentional.
Your Job Is One Income Stream. That’s a Problem.
Relying on a single income source, one employer, and one industry isn’t stability that’s a single point of failure.
Passive income gets oversold as some kind of digital-nomad fantasy, but strip away the hype and the core idea is sound: don’t let one source of money be your entire financial life. This doesn’t mean you need to start a dropshipping business or become a landlord.
Freelancing one skill on evenings. Selling something you already make. Dividend-paying index funds that compound quietly over years. Even renting out a parking space or a room covers groceries for a month. The point isn’t scale it’s diversification.
Every additional income stream is a small hedge against the one that might disappear.
What Income Diversification Actually Looks Like
If you’re employed, check your contract for moonlighting clauses some restrict outside work. But most people have more flexibility than they assume. Start with something you’d enjoy doing anyway. Money motivation alone burns out fast.
It means thinking about what other value you can create even slowly, even imperfectly.
Investing When Everything Feels Risky
Markets are volatile and the news is relentless, so your gut says “wait until things calm down.” Your gut is wrong.
Here’s my honest take: trying to time the market during economic uncertainty is how people miss the best recovery days. The IMF has noted that long-term investors who stay consistent through downturns tend to outperform those who move in and out of positions based on fear. The data isn’t ambiguous on this.
What “Low Risk” Actually Looks Like Right Now
Low-risk doesn’t mean no-risk. It means diversified, consistent, and boring. Think: broad-market index funds, Treasury I-bonds (if you haven’t looked at these, you should), and regular contributions even tiny ones on a fixed schedule. Dollar-cost averaging into an index fund over 12 months beats trying to pick the perfect entry point almost every time.
Boring investments beat exciting ones. That’s not pessimism it’s just what the returns show.
Why Staying Invested Matters
- Missing the best recovery days costs more than you think pulling out during a downturn often means missing the sharp rebounds that drive long-term returns.
- Dollar-cost averaging works investing a fixed amount on a regular schedule smooths out volatility and removes the pressure of timing the market.
- Consistency beats timing long-term investors who stay the course through downturns consistently outperform those who move in and out based on fear.
- Boring is profitable broad-market index funds and low-cost, diversified portfolios have a decades-long track record of outperforming most active strategies.
If you’re starting from scratch with investing, $50/month still builds a habit and a position. The habit matters more than the amount at first. You can scale up later. Don’t wait until you have “enough” to invest that number keeps moving.
Debt, Insurance, and the Boring Stuff That Saves You
Nobody wants to talk about term life insurance at a dinner party. But it’s probably more important to your financial resilience than your investment portfolio at least until your net worth is high enough to self-insure.
Debt management during economic uncertainty has one core rule: prioritize by interest rate, not by emotion. That credit card at 24% APR? That’s an emergency. The student loan at 4.5%? It can wait. You’re not morally obligated to pay off every debt as fast as possible you’re strategically obligated to stop the bleeding first. If you need a clear structure for this, the debt snowball method can help you build momentum while you work through balances.
A few underrated protective moves:
- Income protection insurance — if your income stopped tomorrow, how long could you survive? This fills that gap.
- Review your coverage annually — if your life has changed (new child, new home, new job), your insurance probably needs updating.
- Consolidate where it makes sense — sometimes rolling multiple debts into one lower-rate loan genuinely saves thousands. Run the actual numbers.
The boring financial decisions insurance, wills, beneficiaries are boring because they work.
One more thing: check your beneficiary designations. It takes 10 minutes and it’s the kind of thing people forget until it becomes a family tragedy. I’m not being dramatic. I’ve seen it go wrong.
The Priority Rule for Paying Off Debt
The Money Mindset Nobody Talks About
Here’s where most personal finance advice falls apart: it treats money as purely mechanical. Earn more, spend less, invest the rest. Clean. Logical. Totally ignores the fact that humans are not robots.
Financial resilience is as much psychological as it is practical. Scarcity mindset the constant background hum of “there’s not enough” leads to bad decisions. It makes you avoid looking at your accounts.
My take? The most underrated money skill is learning to tolerate financial discomfort without catastrophizing or numbing out with spending. That’s it. That’s the edge most money management advice doesn’t give you.
Practical Mindset Resets
- Check your accounts weekly even when you don’t want to. Especially when you don’t want to.
- Set one financial win per week, not per year. Small targets keep the brain engaged.
- Separate “money problems” from “life problems” not every financial setback means your whole plan is broken.
- Talk about money. With a partner, a friend, a financial advisor. Isolation amplifies financial anxiety like nothing else.
You don’t need perfect financial discipline. You need just enough resilience to keep going after the hard months.
Economic uncertainty isn’t a test you pass once. It’s the ongoing condition of adult financial life. The people who thrive aren’t the ones who predicted the crash or timed the market they’re the ones who had a system and kept running it, even badly, even imperfectly, through the noise.
It makes you stress-spend. It makes you give up on a budget after one bad week instead of just resetting and continuing.
Start Where You Are, Not Where You Wish You Were
So here’s what actually matters. Not the perfect budget app. Not the ideal investment strategy. Not the side hustle with the best margins. It’s the decision you make today even a small one to take your financial life seriously.
But in uncertain times, consistency with small moves beats sporadic bursts of motivation every single time.
Money management in 2026 isn’t about having more money. It’s about making smarter decisions with what you have, protecting what you’ve built, and slowly sometimes frustratingly slowly building something more resilient.
Ready to Take Control of Your Finances?
Whether you’re just starting out or rebuilding after a rough year, the best time to get serious about your money is right now. Explore more guides, tools, and honest money advice on the blog written for real people dealing with real economic pressure.
Your First Five Moves This Week
- Open a high-yield savings account this week.
- Cancel one subscription you forgot about.
- Send one extra £50 to your emergency fund.
- Look at your credit card statement without flinching.
Leave a Reply